Monday, April 20, 2020

Global Macro Thoughts

A few thoughts on the current global macro environment:

- Europe needs to step up. A barbell strategy could be the best way to play it.

- GBP chart is really interesting, what if it contains a larger macro message.

- Single digit oil, inflation is tomorrows problem, it isn't todays.

- Fed is threading the needle to control USD, but it can't answer the demand side.


Europe needs to step up, a barbell strategy for EUR

"Whats at stake is the survival of the European project" - Emmanuel Macron

Without being too alarmist, it appears the EMU is at a key point in its history, and its response to date is insufficient, especially as it relates to its southern members. Europe has hit a fork in the road, provide a safe asset that at the same time assists the southern countries which conveys some sort of symmetry and commitment to the project, or don't, and face the political consequences.

The most recent meetings of European finance ministers was a chance for the northern European countries to really prove to the periphery that the project is worth it. One of the key things the north has to prove to the south, especially in a political context, is the idea symmetry. In terms of perception, the "transfer" has been, the north takes your productivity, and in return you get the north's borrowing rates. So when times are good, Italian productivity is turned into higher German property prices. However, it can be evened out that when an exogenous shock comes, one so big that is existential, the north says, you borrow where we borrow.

Unfortunately, that has not been the response to date. Instead, what the southern countries are seeing is, when times are good, the productivity transfer happens, and when things go wrong, the weakest among us go the ESM.

Europe has a chance to kill two birds with one stone, create a safe asset and prove the merits of the project to its most skeptical members. So far, they have dropped the ball.

The question is, is the ESM and joint issuance interchangeable, the answer as we know is no. Two key issues even if unconditionally has been agreed. First, stigma, and second, Italy has shoulder this debt load. So let's look a few years into the future, say 2022. Things have calmed down, the economy is back at operating around potential. Every six months, the Commission will give the Italians a hard time about their debt being +150% of GDP.

Eurobonds v ESM, comes down to a simple breakdown, even if technicals appear similar with unconditionality added. The point is a perception of political solidarity. Even with the disparity of unconditionality, the negative legacy still resonates and has the perception of treating them as second rate citizens. Europe will miss the forest for the trees if their message is that there is negligible difference between ESM unconditionally and a common issuance scheme.

The bottom line is, Italy thinks Europe was slow to respond to the health crisis when they needed help, which the president of the Commission has since apologized for, and now they are going to be perceived as not helping in a financial sense by forcing them to use the ESM. It is hard to see how there are not significant political consequences to this, especially as the voices who can convey this, already are on the Italian political scene and have a pretty powerful voice. According to domestic polls in Italy, confidence in European institutions has gone down in a month from 42% to 27%.

Europe can still save itself

One of the things that makes Europe so interesting right now is, the flip side of this, if it were to take place, is immensely bullish the EMU and the single currency. With one stone, Europe can solidify its project by extending an olive branch to the south and be a recipient of massive flows from reserve managers and a global savings pool that is desperate for cash like alternatives. The introduction of a safe asset in this environment would be met with massive demand, even from people outside the reserve manager community. Japan for example, is a massive buyer of OATs because the combination of PSPP and a lack of German/Dutch issuance have left OATs by themselves for reserve managers and Asian pensions.

It doesn't even necessarily have to be coronabonds. Vitor Constancio in a recent blog post put forth something interesting. He postulates that the Commission could issue debt under the context of Treaty Article 122.2 which states "Where a Member State is in difficulties or is seriously threatened with sever difficulties caused by natural disasters or exception occurrences beyond its control, the Council, on a proposal from the Commission, may grant under certain conditions, Union financial assistance to the Member state concerned." Either way, the point is, there are technical ways for Europe to have its cake and eat it too. Which is, northern countries not having to joint issue and southern countries would avoid the stigma and get relief. While the situation may be binary, the solutions are not.

If Europe were to invest itself, with the commensurate response this crisis requires, it could solidify the monetary union and encourage foreign flow from reserve managers and global savings. Hard to see how that wouldn't be immensely bullish EUR.

This duality is what sets up a barbell type strategy for Europe. Either they get it right, or they continue down this current path that surely leads to negative political consequences. Do joint issuance, save the EMU from political backlash and introduce a safe asset in time of tremendous demand for cash alternatives. Or, the market prices some nasty tails from the political backlash, which even Draghi in May 2018 struggled to deal with.
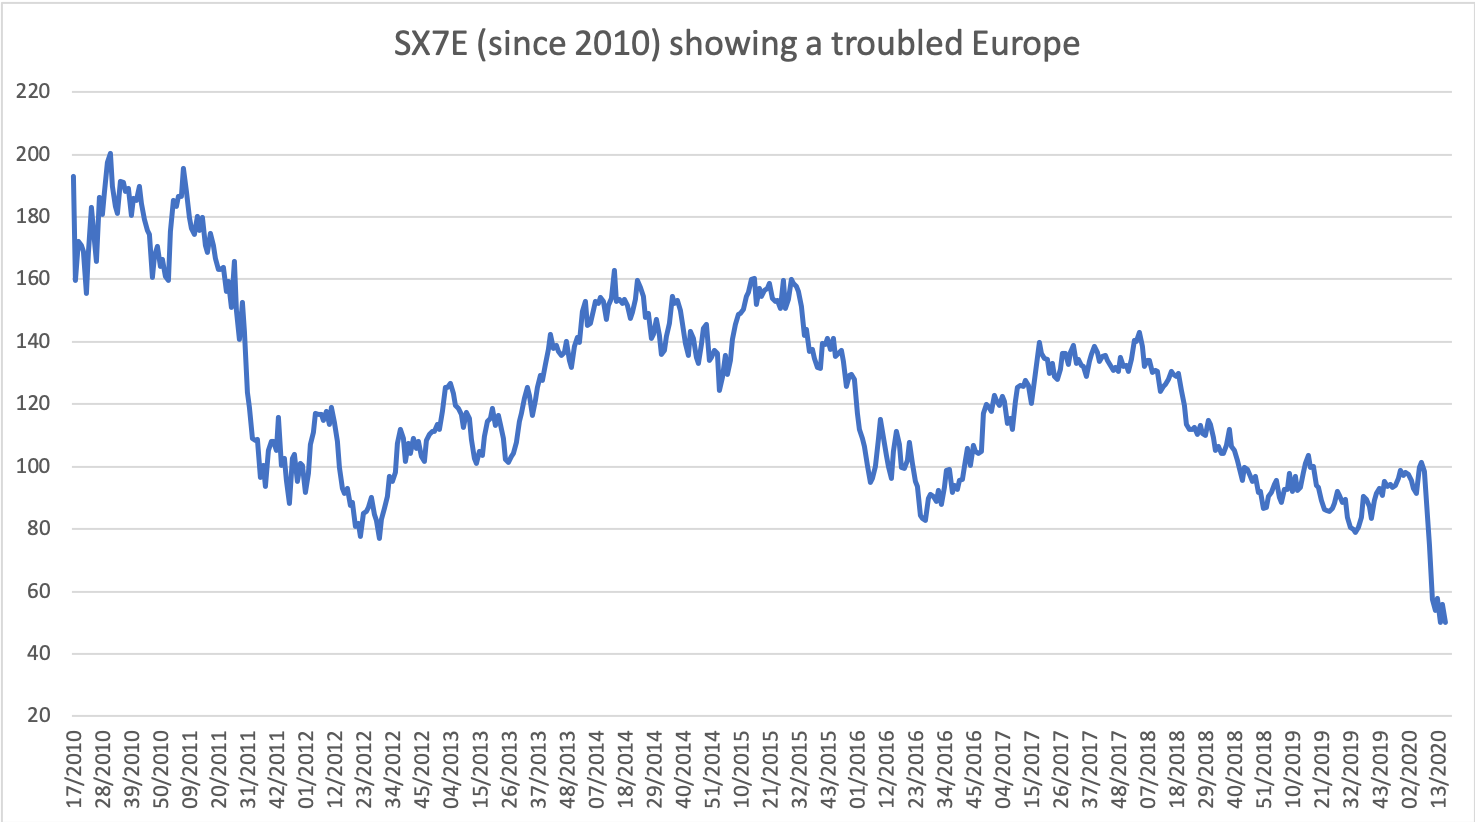


GBP in a world of fiscal/monetary mix, the post Osborne/Carney UK

One of the more interesting charts to me in global macro right now is a broad reading of GBP using effective exchange rates. Since Brexit it has been making a long basing formation.


Typically, in a crisis, GBP comes under pressure as it runs a large external account deficits with high external debt levels. However, despite its initial reaction in darker days of March, GBP has been resilient, even relatively strong. This comes with a very aggressive monetary/fiscal easing that has included a temporary reactivation of a scheme that makes it possible for the BoE to finance public spending directly. So the UK has gone into this shock with an overhang of political clouds from the transition talks with the EU, weak external account (c/a, NIIP, external debt) and has done the most aggressive version of monetization, and with all of that GBP/Gilts keep rallying......


It's absolutely possible that GBP is pricing spillovers from funding markets, and there is no massive GBP breakout coming. With that aside, there could be a broader macro point in GBP that is worth considering. It is possible that GBP is pricing, this aggressive policy mix, as "the right thing." I.e. what if this is the UK's 1931 and breaking the gold standard, which led to a few a years of higher TFP and higher real growth. There is no FX deval this time, but UK policy is being "set free" after years of fiscal austerity and defensive supply side based monetary policy making. 

What did every MPC inflation report say once the bank started hiking rates. "MPCs central projection, therefore, a small margin of excess demand emerges by late 2019 and builds thereafter, feeding through into higher growth in domestic costs than has been seen in recent years." The perception of reduced economic potential from Brexit led the BoE to a tighter posture than it needed to be. 

The UK has lost its Osborne/Carney combination of tight fiscal and hawkish monetary based on a shrinking supply side and has replaced it with an aggressive monetary/fiscal mix. The currency is usually not the outlet to represent such a transition (and maybe it's a poor way to play it), but it could be this time around as this transition seems very bullish, especially v the obvious constraints that Euro countries are facing. A currency is an outlet for economic imbalance. Aggressively trying put an economy back together in the name of preventing further deviations from potential, is not an imbalance, even if the numbers seem big. What if GBP is saying the UK economic response is right......

Short EURGBP seems compelling. UK policymaking have been set free, Europe is still constrained. 90c looks like a decent top and should serve as a good stop.


Oil is going to single digits, inflation is tomorrow's problem

The Saudis and Russian both knew there was no rebalancing the market into this sort of demand shock, and decided it was time put shale in the grave, and they are doing just that. Global demand is off somewhere between 20-30mbd, Cushing is likely to be close to filled up by the middle of May (inventories are rising at +16mbd per week), and rolling shut ins in the US/Canada will begin to take place.

This dynamic has set up the super contango in the oil futures curve, and with few bullets left from geopolitical forces, oil is still a compelling short. One, there is plenty of room for oil prices to continue to fall before shut ins really accelerate and once storage gets overwhelmed that is when you get negative prices in regional contracts as basis continues to be super wide. And because of this current storage dynamic, the market is paying you an absurd amount of carry to be short. The May roll has been absolutely hideous, but it seems like nearbys will continue to trade in steep contango with the just an absolutely vicious rolldown. So oil has no demand, storage is filling up and you basically need to make 20% just to beat the roll, how can anyone be long this thing and yet inflows into USO ETF continue and that is likely the only thing keeping up the June contract. These USO inflows are about to get killed. And they are the only reason the active June contract is still above 20 bucks.


So what are the consequences of single digit oil in a global macro sense. The first thing that comes to mind is the inflation question. I'm sympathetic to the inflationary endgame; disruptions from supply chain regionalization, public policy more focused people with higher MPCs. It is all very plausible, but it will take time.

Supply chains will face political pressure and a reevaluation of the trade off between the wage arbitrage and transportation logistics. But these things take time unless politics hastens the adjustment, which could very well happen.

However, the path to supply chain regionalization and more targeted public policy is with massive labor market slack, an oil price that is single digits and an increased propensity towards savings as covid19 leaves its economic PTSD. Despite massive public sector deficits, it is very hard to see how a massive imbalance between supply and demand in the aggregate will form in this backdrop, even if the supply chain disruptions are worse than many are projecting.

The trading consequences of $10 oil, a few things:

- Breakevens have gone too far. Stocks are not pricing some miracle recovery, as Mike Green in recent post said, the stock market more so represent transactions than information, and the combination of passive and massive foreign savings demand along with a liquidity bazooka all are colluding to raise asset valuations, even into uncertainty. Real yields will likely begin to rise again.

So far these two seem pretty correlated. That could continue, but may not make sense to read too much into the message. The economic imbalance is there is too much private capital going after too few investments, not that there is too much govt spending into too little economic supply.


- USDCAD could go to 1.50. Combination of an oil price in low single digits or even negative (WCS), and what will be a private sector balance sheet deleveraging should put a cap on how far an economic recovery will go. Also the BoC has been pretty aggressive themselves with cutting all the way down to its effective lower bound (0.25%) and doing three pretty big liquidity programs (BA purchase facility, Provincial Money Market Purchase Program, CP purchase program). That is all before they said at last weeks MPR meeting that they will take down 40% of each new gov't treasury bill auctions, and said they're program of purchasing gov't bonds (min 5b a week) could be increased any time. Canada went into this crisis with an economy near potential, as the BoC likes to point out, but it also went into with relatively high levels of household and private sector debt. The combination of a slower private sector response and very low oil prices all with an aggressive central bank could make CAD pretty vulnerable.

Controlling USD is like threading a needle, what about the demand side?

The market seems torn between two camps as it relates to USD, and it is quite binary. This is quite interesting as it seems like a very nuanced dynamic. And again, the demand side is likely being underestimated with not that many alternatives for capital to go. 

A few dynamics:

 If the battle for global savings is US risk assets v EM/Europe or China, US will likely win.

- Balance sheet constraints were a key reason for USD strength in the onset of the crisis as many Asian non bank financials use that balance sheet to hedge/fund USD credit risk. With the Fed flooding the market, local CBs more focused on reaching end users, its hard to see what really aggravates the FX swap market as cross currency basis will trade with a much less negative bias. The effect of UST bill issuance will probably be key in monitoring this. But as a whole, the Fed is getting USD to those who need it, and that could really serve as a cap on USD strength as it has so far. Especially if Zoltan is right and the Fed caps bill yields.

- So Asian savings has to worry less about funding/hedging duration trades, and the Fed is implicitly backstopping many of the instruments they are long, investment grade credit. That means the US is still a relatively attractive place for global savings, especially if this duality of a tame FX swap market, curvature which reduces hedging cost and a Fed determined to protect high quality risk assets, seems like USD is still a decent home for global savings.

- One of the key spillovers of QE is meant to be the portfolio balance channel. However this channel becomes a bit more confusing when everyone is doing it, i.e. no global carry trade. Is real money going to fund EM, seems unlikely, they have no growth and no carry.

Makes sense for US tech to continue to attract capital over Emerging markets. This trade plays on two themes:

1) DM has balance sheet to absorb this mess, EMs do not.

2) In a world of no carry, capital will prefer US given growing asset class in an appreciating currency.


- EM crisis response seems to be correct, but it will require a continued adjustment in the exchange rate. Even, if IMF liquidity facility and an SDR allocation were to come in a meaningful way, that will only give local CBs more room to continue cut rates. If the response remains underwhelming, then places like (ZAR/IDR/MXN) will continue to go through the "original sin redux" as Carstens and Shin have noted. That is the problem with having such a high percentage of your local ccy bond market being owned by foreigners. And, the cut rates/let fx go, doesn't actually incentivize a buildup of domestic savings.....

- So while oil and shutdowns will keep current account balances relatively in tact, as we have seen in places like the Philippines where the Luzon shut down has cut import demand to zero. This gives the BSP plenty of room to get dovish. However, what happens when it opens up, and remittances drop, PHP wont be as strong as it is now with the policy rate at 2.75%. The point is, as unfortunate as it is, this EM adjustment in the exchange rate will likely be structural and the bias will continue to be for USD/EM to trade higher.

No growth/no carry, this could be more structural.


- And as a last one in terms of where capital could go, as we said above, Europe is vulnerable.

Overall: yes, the Fed has done a lot to clean the global USD funding pipes, but it's hard for them to fight the fact that the US is still the preferred destination for foreign capital. And that at the end of the day will likely be the balancing act of USD going forward. My bias is that it goes higher, but the Fed could have established a pretty decent cap by dislodging the USD funding market through these massive liquidity injections.

One point that I think is overrated as a reason for pending USD weakness is the "twin deficit." This likely underestimates how much bigger deficits can get before they worry USD. Ito & McCauley from the BIS showed us that global imbalances look a lot different when key currencies are the unit of analysis and not GDP.


The world likely still lives in a USD smile world. Until a demand impulse from RoW is to emerge, the market will continue to focus on the risk on/off dynamic of how USD can benefit in either, higher risk assets or a flight to safety. I think a key answer in the USD, risk assets etc, will be found in global term premia. Either it rips in response to the massive size of this global easing impulse, or it lags and continues to favor the imperial circle, strong USD and elevated US asset prices.


Thanks for reading, stay safe, best way to be in touch is email, jonturek@gmail.com

Thursday, March 19, 2020

Fed Swap Lines, USD Shortage and a Policy Transmission Problem

Today the Fed made an excellent decision in expanding the list of CBs eligible to USD swap lines.  The point of this note is to try and clearly explain the issues in the current dollar shortage and why swap lines by themselves may need to be expanded in terms of definition because the actors are not the same they were in 2008. The USD funding market is 13t dollars according the BIS and it is under huge strain. Today's announcement of the Fed adding nine more CBs to the central bank swap line program is huge and will hopefully alleviate some of the issues below. As a side all the credit for this post goes to Brad Setser and Hyun Song Shin as they set the standard on these dollar issues and how they impact the real economy.

USD is the dominant global macroeconomic variable

To me, the dollar is the dominant macroeconomic variable. In terms of the financial and real economy, the dollar sets the pace. Right now there is this fascinating duality going on where the world in a binary sense is either extremely long USDs via lopsided international investment positions or extremely short them via credit intensive supply chains. The problem is, the world is not binary, it is incredibly nuanced. And what is making it worse is all these things cracked at once. And under the current reaction, the Fed seems to be reacting to old USD world not the one we live in now.

What has the dollar been saying in its reaction to covid19, and what stage are we in:

First reaction (end of February): USD is a risk currency via a massive negative NIIP positioned. As that flow into assets has roared, more and more of it was unhedged. This contributed to an imperial circle of sort which I have discussed in past posts. So what happened, risk markets started to get hit, new flow into US assets stopped and the dollar got sold.

Second reaction (early March): As the pandemic rolled on, supply chains, which were already stretched and vulnerable, began to break. What do we know about supply chains, they are incredibly credit intensive, especially the longer ones. The other thing we know about them, many of them fund in dollars. As they break, they hoard USD for payment and FX basis blows out and CIP deviation furthers. Which is when the Fed comes in with central bank swap lines.

Third reaction (where are now): Supply chains are breaking, Fed swap lines are not frequent enough in an operational sense and they don't reach far enough in terms of jurisdiction. The dollar shortage is becoming more amplified because key economies are left in the cold. The RBI did two yards of USDINR swaps, and 4b was on the bid. Global corps, especially ones that are part of long supply chains, are stretched and desperate for dollars. To make matters worse, there is a transmission problem in terms the Fed's swap lines. Outside of Japanese financial institutions, most of these players are non bank actors who need USD. This is another example of the Fed's liquidity transmission being broken, the problem is, the 13t dollar funding market is in trouble and it is mostly non banks which makes it harder to get them the support needed.

Before we go into the background, here is the conclusion: The Fed has more to do in terms of FX swap lines. There is a combination of supply chain weakness in EMEs and a misdiagnosis of the problem in terms of who actually uses the FX swap market. Since the crisis, it is mostly non banks hedging UST and US credit exposure. The Fed needs to go to the root of the dollar issue, and unlike 2008, it is no longer getting swap lines to the ECB to fix dollar mismatches in the European banking sector. Asian lifers and pension funds are now the massive players and they need much more directional help.

Two key actors and 13t dollar funding market.

1) Credit intensive supply chains

2) Non bank actors who are biggest players in FX swap market to hedge US credit risk

The point is, until today, the Fed was in no mans land re these CB swap lines. The supply chain pinch is in EM and the financials that use the FX swap market are no longer banks playing US mortgages, its non bank actors like Asian lifers and pensions that FX hedge US credit. Neither are getting the help they need. The transmission of these swap lines needs to be adjusted to further ensure effective policy transmission.

Part 1 of the Fed's problem, the 13t USD funding market 

There is an implicit loanable funds framework to this which may not make this so popular, but the basics of it is, USD cross border flows = RoW USD lending to global actors.

The problem global actors have is, this 13t dollar funding market is very fickle and as supply chains have become elongated, they have become more and more credit intensive. This sets up a two part problem for supply chains.

1) The level of the dollar effectively determines how much financing they can do. And as the BIS has explained, this sets off a bit of a doom loop. When there is a credit crunch for these actors because the shadow price of credit is rising, output falls off, which only strengthens the dollar (less economic beta to exports than RoW), and this fire can only be put out by the Fed.


2) When the dollar goes up, financial conditions freeze which only amplifies their need for USD. An example of how bad it is was in India this week. RBI did a 2yard auction in which there was over 4b on the bid. Korea is another example, BoK did a large intervention last night selling USD v KRW and spot rate still went up 2%, only to be arrested by the Fed announcing a swap line to them this morning. These guys are outmatched without Fed/IMF help.


BIS has done amazing work explaining what are the key parts of the 13t USD funding market.

1) The broad dollar effectively shows us dollar funding conditions in the global economy.

2) As Hyun Song Shin has explained, it is also an indicator of bank balance sheet capacity via VaR. Assume the counterfactual to make this point more clear.

"If a global has a diversified portfolio of loans to borrowers around the world, a broad-based depreciation of the dollar results in lower tail risk in the bank credit portfolio and a relaxation of the banks VaR constrain. The result is an expansion in the supply of the dollar credit, through increased leverage."

The point is: if a weakening dollar can expand bank capacity to lend, a stronger dollar does the inverse of that and tightens capacity.

These two things are what connect the level of the dollar to the real economy. As I've said in prior posts, the dollar is a culprit and a reflection about the level of global GDP. On the hand it can impose weakness via shadow credit, and at the same time it can reflect the weakness in global trade and supply chains via a lower beta to global growth. This is the result of a currency that is 50% of global trade invoicing and is only 18% of global GDP. This mismatch between USD representation in terms of US contribution to global GDP and its global usage is only further evidence of how important the Fed is outside of their domestic mandate when the world is in crisis.


Part 2, the non bank financial actors that run the FX swap market

Something I have gone into over the past few weeks, is that Asian demand for USD assets has been relentless since the crisis. So big that it has ballooned into $8t international investment position for Asia. The reason has been relatively simple, it is capacity. Asian real money assets are over 10x the size of their domestic IG market with the Japan the extreme at over 20x. Add on the fact that it was positive carry, and the money flew into finance US deficits, especially in the private sector.

In a prior post I focused on the unhedged aspect of this trade, especially as it relates to Taiwanese life insurance companies. And while that is still an issue, when liquidity dries up the issue expands to the hedged aspect, especially as these guys hedge in the front end to own longer term USD assets.

So what happens when there is a crisis, over 11% of demand for US credit goes quiet (outside of stealth GPIF interventions). And this amplifies the liquidity crisis onshore. The problem is, swap lines go to banks, and the biggest players this time around are non bank actors. And these non bank actors are so big that when they have issues, it is felt in illiquidity onshore. For many of these guys, liquidity in the global money markets = capital market liquidity onshore in the US! So the Fed needs to get liquidity to these guys in order to help restore second and third order liquidity.

This is the importance of transmission. Dollar auctions are nice, but the non bank actors need access to them. If the Fed can arrest pressure here, that will be job done and the positive ramifications will spillover into things they definitely care about, like liquidity in US credit and treasury market.

This is why the FX basis market and the broad dollar index have shown such a strong correlation.


What will the Fed final reaction be, what are the key characteristics of this USD shortage?

I can't underestimate how big today's move is and I applaud the Fed for doing it, it is very necessary. My only fear now is, is not only that this list of 16 CBs is still not long enough, but that the transmission is much more complicated this time around, as supply chains are much more in EMs and the biggest player in FX swap market these days are not banks, its non bank players.

So what are the key characteristics of this shortage

- Within foreign banks, its not homogenous among who funds in USD. Canada and Japan, are not in the same boat as Europe for example.

- The biggest players in the FX swap market are not banks anymore, its non bank actors who use it to hedge longer duration USD exposure.

- Supply chains are breaking and they are more often situated across EM's and EM CBs are being overwhelmed by local demand and massive portfolio outflow. Also EM CBs this time have decided it is better for FX to fall apart than to hike rates.

- Real yields are spiking as they are everywhere

- Oil is making it worse, petro dollar players are in trouble as oil players are all in USD.

Conclusion: The Fed has two key things to do after today's necessary decision. 

1) Make sure transmission of swap lines is working, it is harder in this crisis because banks are not the main problem. Non bank actors are that big now, and they can exert pain in liquidity terms in far reaching ways, which is effectively what we've seen.

2) EM's need help now. The Fed and the IMF need go past the 16 CBs currently on USD swap lines. This problem is only amplified as EMs are not hiking rates this time around as they are letting exchange rates be the punching bag.

best way to be in touch is jonturek@gmail.com

Wednesday, March 4, 2020

The Gravitational Pull of the Lower Bound

The idea of this is not to say the world is ending, or that this is an economic forecast in any way. The point of this note is to offer a different perspective on what is currently weighing on the bond market as the broader context of these under-appreciated technicals seems very important. Also, if these factors are right, and continue to push yields lower, it will end up being very supportive for asset prices, especially in the US.

We are at a critical stage in monetary policy in the US. Three key themes. 

1) When r* is this low, there is an innate bimodal distribution for the funds rate, you are either close to neutral or close to 0. And this is the exact setup the market is facing now, does 50 do the job or does 0 beckon. Did the Fed adjust to a shifting goal post in terms of neutral, or is this part of a "natural" move to 0. We will soon find out and it should create real two way action in Eurodollars going forward.

2) There is considerable research to suggest the ZLB is binding a significant percentage of the time when r* is low. Ben Bernanke has made this point multiple times over the past year, most recently in his keynote speech at the AEA conference in January. Bernanke's point was, assuming r* in the US of 1%, there are Lower for Longer (L4L) policies the Fed can do to add policy space and minimize ZLB episodes. His forecasts show that under a traditional Taylor rule with 2% inflation target and r* of 1%, the lower bound is binding 30% of the time. Even assuming L4L policies, that number is still around 20%. The point is, ZLB episodes are extremely difficult to avoid when r* is this low, that's just the nature of the beast.

3) The other source of this gravitational pull towards 0 is, divergent interest rate levels are innately unsustainable. The Fed wants to react domestic factors in line with their dual mandate of price stability and maximum employment. However, too much of the policy setting is set abroad. As we learned in Jackson Hole this year from the terrific Riders on a Storm paper, around 50% of the of the monetary policy stance comes from global factors. This goes a long way in explaining that despite 50 year lows in unemployment and inflation not far from target, the Fed has now cut 125bps in less than a year.

Conclusion: 

The market and FOMC are entering a critical phase which seems bimodal in an outcome sense. Either, the Fed was able to instill enough accommodation to reduce ZLB risks, as their research suggests, when close to 0 act swiftly, or, the natural forces of this very low r* world are exerting their natural forces and bringing down the funds rate to its lower bound. Said another way, will the Fed be able to adjust for lower r* and tighter financial conditions, as they did in 2019 in response to tariffs. Or, have we reached the point of no return in terms of the immense pull of a binding lower bound.

The Fed is in no mans land between neutral and 0, the power of the zero lower bound pull

One of the things that is most interesting at the moment is the sheer speed at which the market priced Fed rate cuts. There is a cascading feeling to US bond yields at the moment and the reason is deeper than just uncertainty about the current shock.

The problem the Fed has, and why the market has gone so fast in pricing implieds, the Fed is is no mans land. As we have seen in research from places like DE Shaw, when r* is low, there is an innate bimodal distribution to the funds rate.

The sum of it is, you are close to neutral or at zero.


As the shock has evolved the, market has transitioned from pricing natural negative permia of an asymmetric reaction function, to the pressing need for rate cuts to arrest the decline in financial conditions. As the market prices a lower policy rate, the gravity of the lower bound begins to kick in and this vicious rally in bonds begins.

One of the reasons the Fed was relatively aggressive last year in lowering the policy rate was because of the well known research that when you are close to the lower bound, you have to be aggressive to minimize the chances of hitting it. This is why the research topic du jour in the Fed framework review has been about creating policy space in a low r* world. The problem now is, this shock is different than tariffs via the exchange rate channel (limiting USD upside), and the Fed has already played the insurance card. The gravity of the ZLB is, 125bps in rate cuts over the course of the year is no longer insurance. I.e. part of the reason this move in rates has been so swift is, the market has to consider that the "adjustment" period is over and zero beckons. The idea that Fed can continue to recalibrate policy relative to their celestial stars is getting exhausted. That doesn't mean they cant cut 100bps and say job done, but the real message of this move in market pricing is, the Fed is caught in no mans land and "gravity" or the binding ZLB will continue to pull them to zero in the case of shocks.

This chart is Bernanke's estimates for ZLB frequency under a traditional Taylor rule model and 2% inflation target. As we know from his work with Kiley and Roberts last year, that under assumption that r* = 1, the ZLB is binding around 30% of the time. Even with some lower for longer (L4L) policies like QE and forward guidance, the ZLB is still binding around 20% of the time. The point is, especially under more traditional monetary policy settings, it doesn't take much to push the Fed back to zero.


So what do we know so far, 2 things:

1) When r* is low, the bindingness of the ZLB bites and is like gravity pulling interest rates to zero

2) When r* is low, there is innate bimodal distribution, you are either at neutral or zero

Now, this is pretty powerful on its own, but what if r* is even lower. Both the DE Shaw chart and much of Bernanke/Kily/Roberts, have base assumption that r* is 1. What if its 0....

One of the biggest differences between 0 and 1 in terms of the level of real neutral rates is, there is more room for L4L policies to contribute at r*=1 in terms of adding policy space and limiting chances of ZLB episodes. Bernanke said, if the nominal neutral interest rate is between 2-3%, which is what is assumed for the US economy, then L4L (lower for longer) policies can add up to 3% of policy space at the lower bound.

However, "if the nominal neutral interest rate is much lower than 2 percent, then the model simulations imply that the new monetary tools—while still providing valuable policy space—can no longer fully compensate for the effects of the lower bound."

So now we have to add a third finding, if the r* is actually closer to 0 than 1, than the Fed even by adopting lower for longer policies, which they will for sure try and do with their strategic review, will still very much struggle in preventing ZLB episodes.

Another factor in pricing the funds rate, so much of r* comes from abroad

One of the more interesting macro themes of the past few year, which continues to prove itself, is that divergence, especially in monetary policy is unsustainable. There have been two key papers from the academic side that encapsulate this message.

1) Something Kristin Forbes has been talking about since Sintra 2018, there is a global Phillips Curve and that has a massive impact on the slope of any local curve. In her latest paper, a couple months ago, "Inflation Dynamics; Dead, Dormant or Determined Abroad?" Dr. Forbes posits that domestic CPI inflation is increasingly determined abroad.

One of the charts from her paper show, that incorporating "global variables" such as commodity prices, world slack, exchange rates, and global value chains, are necessary in forecasting domestic inflation.

"This chart shows the resulting “error” between actual inflation and inflation explained using the rolling estimates. It shows the superior performance of the model with the global variables (in red) relative to that with only the domestic variables (in grey) and with the domestic variables plus import prices (dashed black)."

If global factors lead to reduced model error in expected inflation outcomes, then obviously global variables are having a large impact on domestic prices.


2) Arguably the star paper from Jackson Hole this year, "Riders on a Storm", shows that interest rates are increasingly correlated to moves other than Central Bank reaction functions and domestic mandates.

"Taken together, the average monetary policy stance explains only about half of the variation in interest rates. The other half of the time, interest rates move for reasons other than a central banks response to the economic outlook."

Variance decomposition of real short term interest rates (calculations by Jorda and Taylor)


The point is, inflation and neutral interest rates are increasingly a globalized concept, monetary policy does not exist in a vacuum. Another example of this, from their paper is how synchronized policy rates have become.

Stance of monetary policy is highly synchronized (calculations by Jorda and Taylor)


Global factors are pushing the Fed, despite the FOMC being the closest CB to its mandate.


So to update again, now we have 4 strong factors anchoring front end yields lower

1) When r* is low, the bindingness of the ZLB bites and is like gravity pulling interest rates to zero.

2) When r* is low, there is innate bimodal distribution, you are either at neutral or zero.

3) If r* is below 1%, the ability for the Fed to minimize ZLB episodes is further curtailed.

4) Low r* has large global beta, from the nominal neutral level of interest to inflationary forces.

If the Fed ends up at 0, what comes next, steepeners never work but they may have to this time

A good place to look at how the Fed will likely respond in the case of conventional policy space running out, is Governor Brainard.

One of the reasons steepeners have been a brutal trade since the middle of last year is, despite their approach of preemptive policy, the Fed has not really been cutting to get ahead, they have been cutting relative to shifting goal posts. This is why the dollar has remained strong and the curve flat.

However, this time really could be different, especially with 10y note yields sub 1%. If the market is seriously going to entertain the lower bound, then we know two things.

First, it will stay there a while. Brainard's February speech shows this, once you get to 0, you stay.

"Forward guidance that commits to refrain from lifting the policy rate from its lower bound until full employment and 2 percent inflation are achieved is vital to ensure achievement of our dual mandate goals with compressed conventional policy space." 

Second, as the same Brainard speech shows, the Fed will consider some sort of YCC via caps on interest rates in the short to medium term part of the yield curve.

Conclusion: If the market has to entertain the lower bound, there are two key things that should continue to favor steepeners. 1) the very front end will continue to glide towards 0 while the belly of the curve is running out of room to rally if part of the response mechanism is going to be caps on the belly. 2) If the Fed were to do YCC type thing, 2s are anchored to the ELB, tenors outside the cap have to price a normal distribution + the floor of caps. Basically, if the market wants to price 0, the very front end has plenty of room to rally, that case is less compelling in the outer parts of the curve in a very mechanical sense.


Thanks for reading. best place for comments and feedback is by email, jonturek@gmail.com

Thursday, February 13, 2020

Imperial Circle Part 2: The Long US Asset/Short Global Growth Feedback Loop

This post will not be based on any specific trade ideas but rather on what appears to be one of the more dominant macro themes out there and one I have been spending a lot of time looking at. Most of the things here are very well known, the world is very long US assets. However, I don't think many people are looking at the interconnectedness of it all, especially as it relates to the real economy. 

The most obvious macro theme is and has been being long S&Ps, USD and bonds. There are many reasons for individually each of these have done well. The question I am interested in is what has them so interconnected, self fulfilling and sufficient in terms of durability.

The basic point is, there are two ways in which the not only do bonds/S&Ps/USD do well on their own, but actually create a positive feedback loop for each-other that has proven to be remarkably durable. The consequences have been massive US asset outperformance and lower global GDP mostly via the dollar. 

This is what is unique about this version of the imperial circle, it leads to divergent outcomes between global growth and US asset prices. The US has been rewarded for being the only place able to absorb this massive global savings glut, mostly from Asia. The knock on has been, money floods the US, USD rises and then hurts global growth. Not only do these coexist but they have become self reinforcing in a way. Anyway, this my attempt at connecting the duality of money flooding US risk markets and the dampening effect the strong dollar has on global growth as they are clearly connected.  

Two interconnected factors, capital flows and economic effects:

1) Capital flows

The $8t Asian saver (Asia IIP) has neither yield nor capacity to deal with the size of domestic savings, so they need to be exported. What has capacity and yield, the US' balance sheet in both corp and UST. So what happens is simple, Asian savings flood the US. However, these pensions/lifers in Asia would rather not take currency risk, and post 2018, FX hedged yields in terms of USTs were actually negative relative to domestic JGBs KTBs etc. 

So two things happen as the US is still the only place that can take this capacity. Asian savings move out the risk curve and takes more naked FX risk. And they did both. We know this in places like Taiwan were lifer assets are 150% of domestic GDP, now over 20% of their book is FX unhedged. 

So when FX basis crushed yield pickup in the US, Asian savings transitioned into IG/take more FX risk. 

(data from IMF GFSR 2019)


This chart is a ratio of Lifer assets relative to size of domestic corp bond market according to the IMF. As I've seen Mark Dow post on twitter, there is a massive global asset shortage, it's very pronounced in Asia and it has forced this money into the US. Pretty much for all of surplus Asia, the size of lifer assets is +10x the size of their domestic IG market, with Japan the extreme at over 20x. 


2) Doom loop in terms of lower global output

There seem to be two key parts to the dollars relation to the global economy. The way this ties into asset shortage part is, demand for US assets has been an important factor in USD strength. 

One, we know USD tends to do well in times of weaker global growth because the US is by far the least levered DM economy to China. DM exports still account for +20% of GDP, in the US that number is closer to 12%. One of the reasons that structurally growth is so low is because global trade is not the engine it once was and DM is just as levered to it. This is why the market is crying out for fiscal, there needs to be a composition shift away from NX to C+I in terms of GDP. Anyway, the point is, the dollar tends to outperform when global GDP is weaker because it is less exposed to global trade.

The other angle is, the dollar itself can hurt global trade and output. This is Hyun Song Shin at the BIS and Gita Gopinath when she was at Harvard. Gita takes the global invoicing angle and Hyun looks at it from a financing perspective. The focus of Hyun's recent paper in October is, a broad appreciation of the dollar dampens international trade by weighing on the operation of credit intensive global value chains (GVCs). 

From Hyun, USD inverse relationship with global trade.

shin speech.png

If we combine these two angles of (2), one that the dollar outperforms when global growth is weak due to lower beta, and that the a strong dollar can "impose" global trade weakness via the credit supply channel, a pretty brutal doom loop is formed. The dollar rallies because global growth is weak and then imposes pain on GVCs which makes global growth even weaker and the dollar rallies more etc.

As Mark Carney said at Jackson Hole last year, this is a natural problem with the US share of global GDP shrinking but USDs role is not.

This chasm between US as percentage of global GDP and the role the dollar plays is structurally disinflationary. 

"These dynamics are now increasing the risks of a global liquidity trap. In particular, the IMFS is structurally lowering the global equilibrium interest rate, r*, by: - feeding a global savings glut, as EMEs defensively accumulate reserves of safe US dollar assets against the backdrop of an inadequate and fragmented global financial safety net; - reducing the scale of sustainable cross border flows, and as a result lowering the rate of global potential growth; and - fattening of the left-hand tail and increasing the downside skew of likely economic outcomes." - Mark Carney 

(data from Mark Carney JH speech)


Combining the rush of foreign capital into the US with the strong dollars global effect

Now we add in (1) and the fact that all this excess savings is going to basically to one place, and you have a new sort of imperial circle but one that is slightly different mechanistically than the one Soros diagnosed in the 80s. But, one that is also creating this sort of feedback loop, however this one is connecting the financial economy and the real one in a very divergent manner. 

Soros Imperial Circle: combination of high rates, fiscal and strong dollar all together create this virtuous circle.

Current dollar feedback loop: a strong USD, lower global growth and the global savings glut feed off each other in way that suppress real interest rates and elevates asset prices.

The current regime offers stronger durability

Eventually what broke the imperial circle was excess dollar strength. However, there is something fundamentally different now, the low neutral rate world has been effectively making sure this dynamic of flooding US markets continues. So what happens:

Real money buys US financial assets:

Step 1: credit tightens and stocks go up

Step 2: dollar goes up

Step 3: Even though risk is bid, bonds actually go up in price because they have to price the second derivative, strengthening USD and the negative effect that has on growth.

And step 3 shows how this cycle continues in an immensely durable way. The dollar and the bond market effectively keep each-other in check. And of course, given the low neutral interest rate world and asymmetric monetary policy response function, the Fed can backstop that bond market reaction. Which is what we saw in 2019. The Fed had to cut to stand still in an FX sense given what effect the tariffs were having and the Chinese using the exchange rate as a shock absorber. 

So the dollar goes up, which triggers a stronger and flatter bond market, which keeps the dollar in check and excites asset markets. That is the durability element. 

Conclusion:

The US is in the process of a monster sucking in of capital from the rest of the world. This is very easy to see in the IMF BoP data which basically shows a 1:1 match of big positive NIIP positions equaling out in the US' negative one.Basically the world saves a lot and then invests in US because it has the combination of best growth and maybe more importantly, the most capacity.

Global NIIP v US (ex Taiwan, which is fifth biggest in the world)

(data from IMF)


Then we combine the current dynamic of these two forces: the US sucking in global savings and the dollar reflecting/contributing to lower outcomes in terms of global output. It seems like the one of the biggest macro dualities effecting global markets and is it very durable as the feedback loop is very well reinforced. Savings come to the US, the side effect of that is USD constrains global growth and that reinforces the short GDP trade which is long duration and USD. 

The question now is, what ends this regime, rate differentials haven't mattered yet


In theory, the dollar should have been a compelling short for much the past few months as it set up in such an asymmetric fashion. Either growth around the world was going to pickup or the Fed was going to cut more. Interest rate differentials have topped in the developed world and the dollar will have to price that. Neither have really happened, and DM rate differentials continue to narrow. 

In a low r* world, with most of the developed world at the ELB, in risk-off periods the Fed is the only ones with ammunition. This fear was very prevalent last year, so much so that it forced the ECB to get out ahead of this potential narrative by cutting and more importantly trying to push out the perception of the lower bound in order to keep the EUR capped into Fed cuts. This eventually died out after the September GC meeting. 

Looking at things now however, their fear may have have been misplaced to an extent as narrowing interest rate differentials post facto are having almost zero effect on exchange rate valuations. The question is why. 

The basic idea is, we may have transitioned from measuring the degree of rate differentials to once we establish them, it's about leveraging them out the risk curve. FX has become much more sensitive to capacity in terms of savings absorption than rate differentials in pure isolation, especially in DM. Japanese real money is not going to repatriate because the differential between JGB yields and USTs is narrowing, the problem the GPIF has is not only yield, although mismatch is huge problem for real money, but the other problem is there are not enough assets for them to invest in at home. As the chart above shows, in Japan lifer assets are more than 20x the size of the domestic IG bond market......

The broad dollar recently has been more correlated to relative risk asset performance than yield differentials.


With that in mind, what are the two things that can change this dynamic:

1) US idiosyncratic risk that causes US equities to underperform global peers. 

2) Global growth pickup led by China as the US less levered to Chinese growth than everyone else. 

We can see (2) in the correlation between rising USD and lower global r* via Laubach Williams estimates. 

(data from NY Fed)


The dollar is a both a result of a disinflationary world but also is a culprit in it.

This is a bit confusing but I think it is one of the most important points. I think Taiwan is a very good example of this. Basically, within the current account there is war between the financial side and the goods side. The goods side does poorly in this low NGDP world as agg demand is low. However, the financial side is effectively short these outcome via long USD exposure and a massive duration position in US fixed income. 

What would happen if 2017 reappeared and a Chinese led demand spurred a reflationary episode that pushes up global GDP and global trade and inflation. One would think in that world, USDTWD would be a sell as Taiwan being a a key supply chain would be a large beneficiary of this pickup in global trade volumes. However, and even in the context of a good risk environment, that could pose a problem to the Taiwanese economy. The lifers have a huge effective long USD exposure via over 20% of their foreign asset position FX unhedged. Brad Setser has done amazing work on this and he shows that if USDTWD were to drop 10%, the lifers would incur over 12.3b USD of losses and they would need to rollover the hedged part of their book even as they were taking losses on the unhedged part, that reduces their capital.

Taiwan is of course an extreme example of this, especially in terms of unhedged risk as the CBC has used intervention to protect the lifers. However, it is just an extreme example of a prevalent trend, Asian savings is short their own real economy. Surplus economies in Asia still get +50% of GDP from exports.  

In its current form, the second derivative of this trade is in a sense hurting their domestic economies via the dollar. 

Short NGDP = long US assets. This chart is US NIIP v SPX/RoW equities ex US. 

niip v spoos.png

To conclude, to me there are few takeaways from this:

1) The world has a short global growth position on via the US on the financial side, while on the output side is still highly levered to it via high export dependency. 

2) There is a massive global asset shortage that is forcing the most money into the place with the most capacity. It is also rewarding it via the currency. 

3) This phenomena is creating a self fulfilling loop in which US equities, the dollar and the bond market reinforce each-others strength. 

Money comes into the US to buy financial assets => hedging costs become prohibitive so more is unhedged => USD stays strong as their immense demand for it from the massive global savings pool => because of USD strength and the effect that has on the global economy, the bond market stays bid and flat => low and flat curves force money further out the risk curve and this circle starts again. 

Monday, May 14, 2018

Vale for now: Neutral Rates, "Symmetric", and EURGBP

I think there are a few interesting things happening that could make the summer quite exciting.

1) Talk of higher neutral rates is deafening. Dudley is entertaining a 3% r* in the US, even in Europe despite this slowdown in economic momentum, Coeure gave a fantastic speech (no surprise there) on the possibility of a reverse hysteresis type phenomena. Given this context, there are some interesting trades in the ER complex and EUR rates. In general, the market is clearing out short vol positions one by one. First US equity vol, then EM via USD, and next will be vol in EUR rates.

2) As I have been writing to a few people recently, there is an interesting dynamic going on between the ECB and Fed. Basically, given the Fed's desire to get to neutral in the face of this fiscal juice over the course of this year AND next, and an ECB still crushing global term premia, we are in the midst of a persistent flattening of the US yield curve. I wanted to suggest that as front month ECB implieds begin to steepen again after this softening of inflation, you could actually begin to see the US curve steepen. I had thought this could create a favorable dynamic for being short EURUSD or long USDCHF. The thought was, either the ECB continues this dove loop with its continental peers (Rix, NBP, etc) or they actually end up giving the Fed more scope to hike by beginning the process of allowing the forwards in the curve to start removing at least some of this term premia crush. Effectively, a term premia transfer from the steeper EUR curve into the US', especially as the ECB can ill afford the end of the Feds hiking cycle. The trade has worked, however, neither really has happened. Yes, the ECB still seems like the key central bank player in terms of dominos, but I believe this "either or" to quote Kierkegaard, can be expressed differently. Long EURGBP.

3) The reaction post the Fed's May policy statement was all about the usage of "symmetric." My first interpretation was, so what, Evans has been talking about this forever and even a likely 4 dots guy, Williams, has been talking about it in the context of his desire for price level targeting. So what's the big deal? I am now beginning to think the market reaction was actually more interesting then the usage of the word itself. Using it twice was purposeful, the Fed knows inflation will likely run above target in the coming months as one offs continue to drop out. Given where the yield curve is, and the desire of the board to have a balanced hiking cycle over the next couple years as fiscal keeps us decently above potential this year and next, this seems like an explicit attempt at steepening the curve. The problem is, the curve didn't steepen, in fact, we are back at the lows...... So what does this mean? The Fed showed their hand, and risk in equities and credit have ripped, which means it could be time for some bottom picking in EMFX.

Trades: Long ERZ9ERZ0, EURGBP, vol in bunds. Also, a no touch in USDMXN

Reverse hysteresis and forward guidance, steeper reds/greens and vol in rates

There are two key elements to this trade, first is the role of FX, second is this possibility of a reverse hysteresis in the face of a loss in near term economic momentum. The two are obviously interconnected so well look at it in one shot. Since the beginning of the year there has been a well documented loss in economic momentum in the Euro-Area. In my opinion there are a few key contributors to this. First, China clearly slowed, surveys, M1 and the LK index all point to a weaker first quarter. The balance of how much more softening regulators will allow, maybe not so much given the RRR cut, and the seasonal contributors related to the new year, is likely key. With that said, given EUR economic beta to the Chinese machine, a softer Q1 in places like Germany makes a lot of sense. External demand is still the key marginal driver of growth, China slowed and the EZ felt it. The other element is domestic factors. However, the ECB has been quick to come out talk about the temporary nature of the slowdown. Especially in inflation, we have seen people like Praet suggest it was temporary factors related to, the cold winter, timing of Easter, labor strikes and even the early innings of capacity constraints in the capital goods sector.

In my opinion this is where the opportunity lies, especially given the current backdrop. Praet's super core measure is running higher than current HICP readings. This means, stickier factors do seem to corroborate the ECB's stance that there are little signs of a material softening in domestic demand. Brent has ripped to almost 80 bucks, EURUSD is basically back at ECB staff macro estimates, and China is trying to re-up liquidity; all at a time that stickier components of inflation are largely behaving as expected. This could be why the market hasn't really budged on aggregate ECB hikes and has just pushed them further out the curve. Looking at Z9Z0 in Euribor is very interesting in this light, especially if FX signaling is such an important variable. ERZ9ERZ0 basically can't trade materially lower on further economic weakness and has a lot of upside to a mean reversion in CESI and the chances of a higher neutral rate (which I will get to). If the data will continue deteriorate as external demand does not pickup, EURUSD will continue on its path to 1.15 at a time oil has absolutely ripped, this means reds/greens have to take into account expected value of rising inflation. Or, this loss in momentum really is just "temporary", which seems to be the ECB's version of "transitory." This is what EUR duration also has to take into account, which makes me think Sintra type fireworks are coming to bunds and buxl as vol has gone to ridiculously low levels. If further econ n/t weakness is priced in FX, duration has to discount an increase in inflation expectations given oil and EUR moving at once. The asymmetry in shorting EUR FI looks pretty decent. This is all at a time scarcity may force a July decision the ECB may ideally want to avoid. Then there is the increased chances of reverse hysteresis kicking in and the limits of forward guidance which we can now get into.

The reverse hysteresis aspect is quite interesting and will play a key role in my FX idea below. Coeure in his speech last month noted that weighing hysteresis on general potential models has proved to be very tricky to flat out wrong in the post crisis world. What we are seeing more and more of is, potential just seems to move with cyclical fluctuations of aggregate demand. This means, in the post crisis world, we are too often confusing "scratches for scars." The ramifications of this for policy is quite interesting. Coeure of course only addresses it within context of current ECB stance, however, it does open door for some interesting hypotheticals especially in the current backdrop. What could happen is, as growth picks up again and inflation gets back closer to target, the market will have to take this idea much more seriously and likely add a lot more ECB hiking scope; maybe r* is more positive than we currently think......  The added part is, Draghi was asked about this in his most recent presser, and instead of entertaining a temporary overshoot in inflation, he opted for the higher neutral rate answer. If he wanted, that could of been an clever way to further the EUR sell-off and he didn't take it. All of this makes it hard for me to be EUR bearish, in fact, quite bullish in some crosses in spite of the steep fwd curve.

On forward guidance. The BIS did an interesting paper recently on forward guidance and the signal value of markets. Going through the references I saw a Coeure speech from last year that I slightly recalled. Given his recent stance and the worries he has re overextending the current forward guidance framework, it was interesting to go back. In that speech, he quotes an interesting Stein paper from 2015, on the time consistency problem with gradualism. The context of this for the ECB is of course on the current forward guidance stance acting as an anchor on rates vol. Constancio has explicitly said the biggest thing that scares him is a rates tantrum. The problem, as Stein notes is, a policy with the primary goal of controlling rates vol won't work over the long term, especially as their assessment of the progress of inflation evolves. Stein coins this as a problem with gradualist equilibria. Coeure is worried about the role it will play in a reaction function sense as the economic assessment evolves. Over the next few months, the ECB could not only be facing scarcity in PSPP, but also reaching the effective time limit in its goal to keep rates vol completely non existent through its current forward guidance framework. What's worth noting is, these things could very well end up happening at the same time.

EUR rates have to deal with inflation that can really only go one way from here at a time both the APP and current forward guidance framework seem to be closing in on their respective limits......
Summer fireworks are coming.

This all should mean EURGBP goes higher


Part of my issue in the last post was my lack of respect for geo-political events, especially in Russia and the Korean Peninsula. Given the fairly poor political dynamic in the Euro Area, it seemed like a good idea to use a cross who's political economy is just as shitty. Brexit is a soap opera that continues to weigh on UK sentiment, especially on the investment side, and the possibilities of an election being called this year are likely real. Of course, politics is not the reason why I like this long. If you recall, from last post, my -USTs+Gilts idea, it is quite similar. I am playing the chance that the respective equilibrium neutral rate is going in the opposite directions for these two economies. What seems to have happened is, sterling got two key things that have now changed. First, the BoE was able to establish a bid by convincing the market of a steeper SONIA curve through forward guidance. Watching short sterling implieds go from 90% to no May hike, puts a big dent in Carney's ability to  establish meaningful scope over the forecast period. The other element was the general tide of liquidity emanating from the Chinese fiscal expansion that fed the world in 2017. Now, survey sentiment is dropping rapidly, capacity is tight, inflation is falling faster than the BoE originally thought in November and Brexit refuses to leave the headlines. A cyclical change in expected potential does not look likely in the UK.

The other element of this trade, and what makes it in my opinion quite asymmetric, is the ECB-Fed dynamic I was talking about in the beginning. Basically, we are in a place where the ECB seems to be in control of how much Fed scope we can have given the effect of QE on term premia. What seems to have happened is, the loss in Euro-Area economic momentum pushed off ECB implieds further out the curve. In turn, we got a higher probability of a APP extension into next year. This creates a tricky dynamic for the Fed which is de facto relying on the ECB to get on with it to help get term premia off this crazy low level. So ECB implieds in whites go to zero, US yield curve forwards cant price any let off, and the relentless flattening continues as the Fed goes with the dots. So the question is, is this situation becoming quite binary and if so, how does EURGBP win either way.

The most likely situation to me is, contrary to current market pricing and sentiment, over the next few months, the ECB hiking cycle could actually be priced earlier than current the EONIA curve suggests with APP going through a more serious wind down. If that is the case, Euro should explode against sterling as the market dynamic of last summer looks set to return; doubting the BoE and a further deterioration in the political economy. However, lets say the other possibility, which is quite high in a probabilistic sense, occurs. The ECB has no let off as inflation remains subdued, the Fed keeps going and US 2s10s is 0 by year end. In that case, the market has to price the end of the Fed hiking cycle at a minimum and at max price a recession a lot more seriously as this will likely coincide with global growth that looks more like Q1 given that the ECB couldn't move. The UK economy, which is already at/near potential, likely is the first to go into recession and BoE has to cut, all while DFR is still stuck at -40bps, the ELB, and FX has to price it....... The other element of course is relative neutral rates as discussed above. In my estimation it seems likely that low potential in the UK is here to stay for now and the Euro Area economy may actually have a steeper hiking scope than is currently priced or expected. Given the asymmetry in my view, a 1y parity one touch, which currently trades for 13.5, makes a lot of sense. Given how steep EUR fwd curves, stuff in exotics is not that exciting, which may mean riding spot is the best option. However, I think given the power of these dynamics, this thing could really begin to move.

Back to the Fed

As said above, the Fed's communiqué from the May statement seemingly failed. The combination of adding emphasis to "symmetric" and having hawks like Mester come out and say gradualism should be the approach even in the face of overshoots in inflation from target suggests, the Fed is making a conscious effort to get the curve steeper. Fiscal is going to juice this year and next, and they want a balanced hiking cycle to keep it in check. However given current curvature, its hard for implieds to price much in scope given the fact the Fed wont move at inversion. Now, the Fed is really showing the market they're paying attention to the curve and seemingly cannot control it. This means, the market now knows the Fed will struggle to add scope to implieds even in the face of higher neutral rates and this massive fiscal boost. This effectively means a forced elongated stay at "policy is still accommodative" in a relative sense; risk assets have taken note of this as spoos have broken out. Given my opinion from last time is unchanged re the effect of fiscal and trade serving as the reverse QE, I am not bearish USD as the scope may exist, but it does mean I struggle to see how a swift 2014 type move could happen. If that is the case, some of the punishment in EM looks a bit overdone. Dollar Mex 6M 20 no touches trade for 25. The Fed will struggle to establish hiking scope until the ECB moves, this gives us time in the n/t for a swift move lower in USDMXN. This is the shortest time horizon trade, but the move could be quite swift. Expiration does encapsulate the July 1st elex, however given AMLO's 20pt lead in the polls, it looks like politics may only be tailwind. The other element is, NAFTA. Does Trump really want a two front negotiation while he deals with China, I doubt it. EM liquidity will begin normalize as public external balance sheets are not nearly as bad as '14. And given the above factors, MXN looks like it should be one of first beneficiary.


End on a longer term story, rebalancing in China 


What has really interested me over the past few weeks has been the relative strength of Asia FX given this broader rally in USD. Part of it is political given the promise of denuclearization of the peninsula, but there seems to be more. Another striking economic development this year was seeing China's current account go into deficit. Of course a lot of it was on more temporary factors such as, tourism related spending and a decent swing in the goods account. However, this move in the external account does seem to jive well with China's broader goal in getting consumption as a much higher percentage of GDP. In the face of this rather large move in the current account, a big compression in the front end spreads v US rates, USDCNH has not done all that much since the end of March.

Now we can look at this from the broader structural setup of the global economy. China in its quest to become a more consumer centric economy, at a time the US is trying to get manufacturing as a higher percentage of its output. The facilitator of this is a relative rebalancing in the exchange rate. To go along with this, China wants to issue for BRI in yuan. So someone has to finance this deficit through the capital account and contribute to the sprawling belt and road initiative; GPIF can do those things. It is very interesting that over the past year, in terms of JPY/Nikkei correlation, CNHJPY has better r^2 than USDJPY.

This relative rebalancing of output composition of the worlds two largest economies has wide ranging ramifications. First thing that comes to mind is term premia, as the recycling of Asia trade surplus' is slowed. This is why having a short yen element makes a lot of sense in this structure. So the way to play this longer developing story, which seems to have already begun, in a highly convex way is maybe through a 2y 20 one touch in CNHJPY. Fwd curve is very giving for betting on CNH strength, especially against yen. Which means, this relative economic rebalancing which will likely occur most through the exchange rate, you can own at 15:1 payout.

This will likely be my last post for a while, thanks for reading and for all of the engagement.

jonturek@gmail.com